Video wird geladen...

Video konnte nicht geladen werden

Zur Startseite

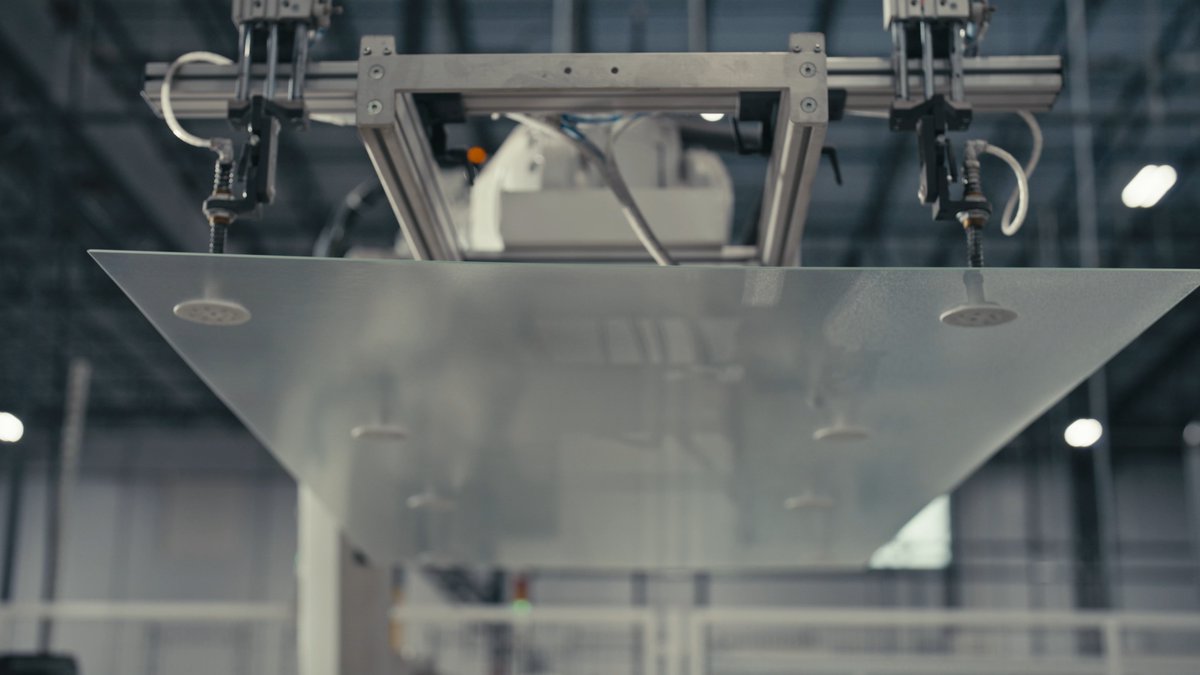
Five layers. Seventeen minutes. One structure built to last for decades. This is Stage 4: Lamination. Heat, vacuum pressure, and precision engineering transform glass, EVA, and solar cells into a fully sealed solar module ready for the next phase of production. This is where individual components become energy infrastructure.

92,377 Aufrufe • vor 3 Monaten •via X (Twitter)

0 Kommentare

Keine Kommentare verfügbar

Kommentare vom Original-Post werden hier angezeigt

Ähnliche Videos

$TE T1 Energy Energy is the new currency. AI deals are now measured in GWs. Without power, the AI revolution stalls. Data centers are being booted from cities due to energy concerns. Nat gas buildouts? 3-5 years out. Nuclear? A decade away. But data centers are building NOW. Solar is the only large-scale, rapidly deployable energy source ready today. China has a stranglehold. Even $TSLA doesn't make its own solar panels/cells. Enter FEOC rules (Foreign Entity of Concern): Only modules using U.S.-made cells qualify for the 10% domestic content bonus on top of the 30% ITC through 2029. Imported cells? Disqualifies the whole system. US based and large scale fully integrated publicly traded solar cell producers are very few. Actually there's really just two... 🔸First Solar $FSLR ($25B mkt cap) 🔸T1 Energy $TE ($700M mkt cap) T1 Energy $TE -One of the most vertically integrated solar makers in the U.S. -Texas based -Snagged a Texas solar plant dirt cheap post-Trump election from a Chinese firm. -Rated as having one of the most advanced solar manufacturing facilities in the world. -Another Texas plant online next year -Targeting 10 GW solar production capacity. A nuclear reactor makes ~5GW equivalent. That's two nuclear reactors per year. (there is currently only 13GW solar production capacity in the entire US) -Landmark Corning deal (Aug 2025) locks in U.S.-made polysilicon/wafers from Michigan for a full domestic chain: polysilicon → wafers → cells → panels -Zero China-sourced components in disclosures -It's competitor First Solar $FSLR is 36x the market cap. - $TE revenue surged from $3M (24Q4) to $54M (25Q1) to $133M (25Q2). Q3 estimate is $300M. -Turned positive gross profit this year -Poised for a major lift from Section 45X Production Tax Credits under the One Big Beautiful Bill Act -Cash projection: >$100M by year-end -P/S (TTM): 3.87 vs. $FSLR's 5.75 -Stock breaking out of multi-year consolidation -Down ~20% in recent pullback $FSLR is the safe pick. $TE? High risk, high reward. As energy desperation ramps up the move on $TE could be eye watering.

YeahDave

146,661 Aufrufe • vor 11 Monaten