正在加载视频...
视频加载失败
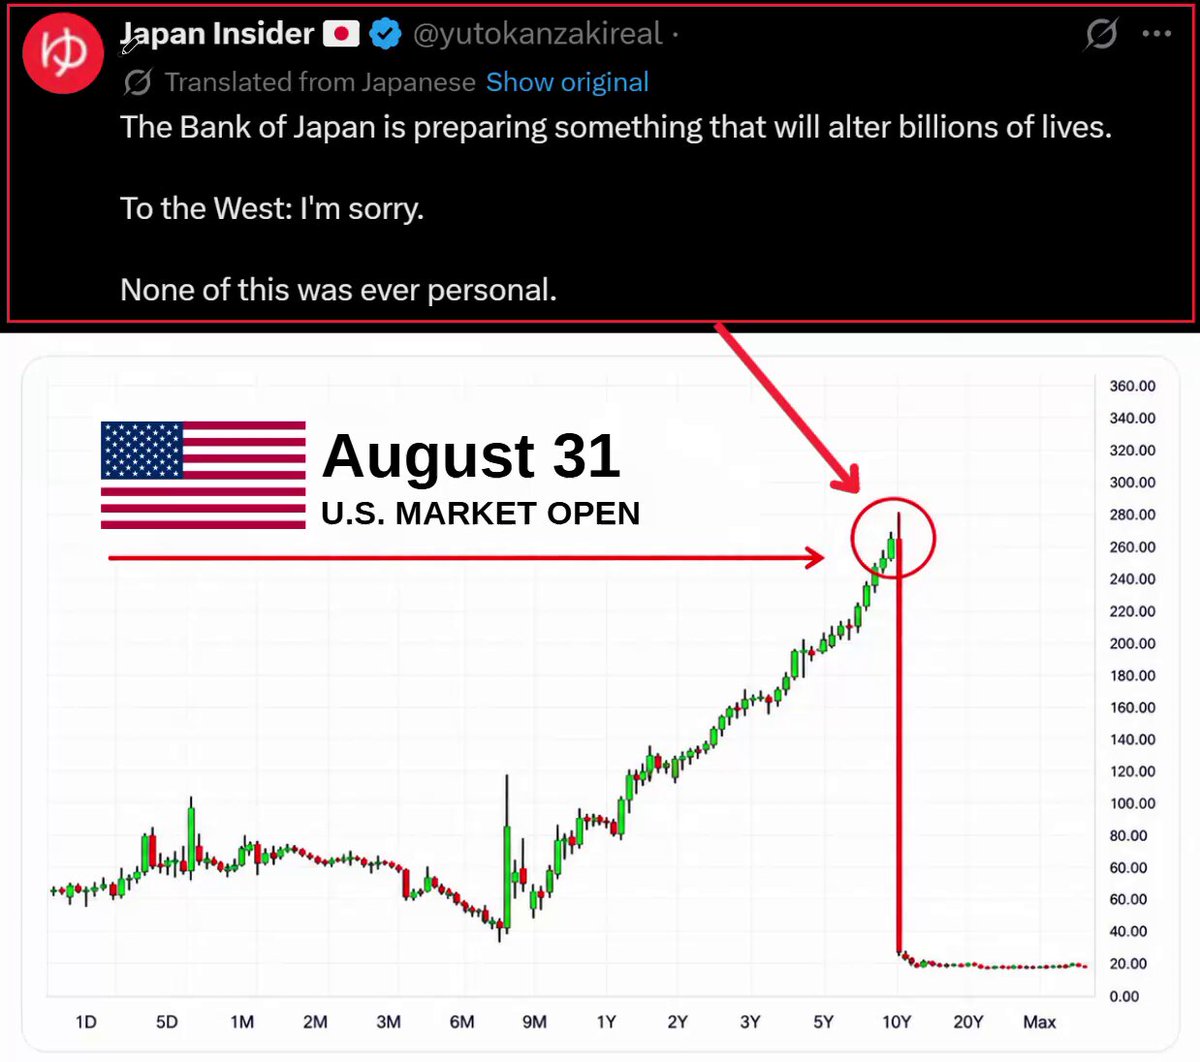
🚨This Is How a Carry Trade Unwind Starts And It Started Today An absolute bloodbath was witnessed in Japan’s financial markets. Short-term JGB yields went VERTICAL today. The 3-month yield smashed 1.25%, highest in 31.5 YEARS and the 6-month hit 1.34%, highest in 31 years. Two years ago these... show more
19 条评论

#AMC

Japan sneezes, global liquidity gets a cold 🤧

What will not help at all is if the FOMC sits and signals "data dependent" and the BOJ hikes and signals 3x25 bp. The parabolic stonk bros are incanting a "no hike" Fed meeting but that is not what they want. If the Fed doesn't hike this week: 1) Yen carry rewind accelerates 2) The long end of the US yield curve goes bananas. A Fed hike is medicine. A Fed fade is poison.

The vertical spike in short-term Japanese yields to 31-year highs is the physical detonation of a massive macroeconomic timebomb. For over a decade, Western markets aggressively leveraged up risk assets using a drip-feed of negative-yielding yen. Today, we are witnessing the brutal snapback: as the foundational anchor of global leverage abruptly reprices, the entire yen carry trade is forced into a frantic, cross-border liquidation. This sudden liquidity shock ruthlessly hunts down over-extended vulnerabilities, perfectly illustrated by SoftBank's catastrophic intraday collapse. Markets spent months blindly pricing in a utopian cocktail of infinite AI acceleration funded by endless cheap Tokyo capital. With both core assumptions fracturing simultaneously, the structural floor beneath hyper-valued tech equities is rapidly evaporating in real time. The real nightmare is that this corporate bleeding is merely the opening act for a much deeper sovereign crisis. Because Japan acts as the bedrock creditor for the American empire, any domestic scramble to chase local yields inevitably triggers a massive offloading of U.S. Treasuries. If Tokyo loses control of this violent unwinding, it will unleash a transatlantic margin call severe enough to completely freeze global credit markets.

Lets gooo .. let’s enjoy how the entire world economy goes down.. all because over leveraged M and hedge funds

Appreciate you sharing this. Your posts always feel measured and well thought out. You and @XfactsmatterX are two market voices I make a point of keeping up with.

You have 10 years of understanding trash. Jesus.

This is nothing, no one said this is "the event"

Tired of hearing about it

So… @leadlagreport was right?

Jaja vai zerar a queda

Appreciate you putting this out there. Your posts often make me look at the setup from a slightly different angle. I get a lot of that same value from following @corp_nick14.

The yen is the tell, not the yield. An unwind shows up in the currency first, because that is the leg everyone has to buy back.

This is the leg the capex models keep pricing at zero: a lot of this buildout was financed short and cheap in yen, against assets that don't pay back until the end of the decade. A 3-month yield at a 31-year high doesn't care how good the demo was. So the 'slowdown' won't arrive as a policy — it arrives as a refinancing. Sentiment can't cancel a facility; duration can.

Huh ? an unwind of carry trade should be bullish for the Japanese market

Insane!!

The real carry-unwind signal is not “JGB yields went up.” It is whether the entire funding equation breaks: JPY funding cost ↑ / BOJ credibility shift / FX volatility ↑ / hedge cost ↑ / foreign-asset return advantage ↓ That is when Japanese capital stops asking: “What can I buy overseas?” and starts asking: “Why am I taking FX risk when domestic yields finally pay me?” If that rotation accelerates, the transmission is much bigger than Japan: JGBs → USDJPY → Treasuries → global duration → equities → leveraged risk The dangerous part is not one bad session. It is that the old assumption of permanently cheap yen funding is becoming structurally unreliable. Once the funding anchor moves, every trade built on top of it has to be repriced.

While short-term Japanese yields have risen sharply toward 1% alongside BOJ policy normalization, exaggerating yield numbers distorts the real pace of the unwind.

Do what. With cash