Beaver
@Beaver_0x • 2,885 subscribers
Ideas that compound. Thoughts on building, thinking clearly, and doing the work.
Shorts

Videos

An MIT professor opened his first lecture by auctioning off a sealed box to twenty-two-year-olds who had zero information about what was inside. No touching it. No shaking it. No hints. Just a box. The bidding started at $1. It closed at $45. He ripped it open. An iPod Nano, retail value $149. The class had priced an unknown object, sight unseen, at roughly a third of its real worth — in about ninety seconds, with nothing but each other's bids to go on. That's minute twenty of session one of 15.401, Finance Theory, taught by Andrew Lo at MIT Sloan. Free. On YouTube. Since 2008. Before the auction, Lo puts up three names on the board: James Simons, a math professor who built the most successful hedge fund in history. Warren Buffett, who runs his empire with a tiny staff and literal high-school arithmetic. Jack Welch, an engineer by training who quadrupled GE's revenue without touching a single equation from his own PhD. Three totally different backgrounds. One shared trait — they all speak the language of finance instinctively. Then Lo tells the room something most finance bootcamps charge $3,000 a weekend to imply and never actually prove: finance isn't really about complex math. It's about two problems only — valuing things, and deciding what to do once you know the value. Everything else, thirteen weeks of it, is commentary. There are no problem sets in this course. He hands you the entire exam question bank on day one and tells you the majority of exam points come straight from it. He says it flat out: memorize the whole stack and you'll pass — except by then you'll have accidentally learned finance. The full thirteen weeks are still sitting on MIT OpenCourseWare, untouched by most people who bookmark it. The lecture is free. Bidding on the box after everyone else already has is the entire course in miniature.
Beaver1,392,154 görüntüleme • 3 ay önce

A small Coke at McDonald's costs $2.29. A large, more than double the size, costs $2.99 — seventy cents more for over 100% more soda. The actual syrup and cup cost McDonald's about a penny of that difference. MIT 14.01, Principles of Microeconomics, Lecture 2. Jonathan Gruber uses that pricing pattern to teach the single idea that quietly explains it: diminishing marginal utility. Your first sip of Coke on a hot day is worth a lot. Your fiftieth sip is worth almost nothing. You'll pay real money to go from zero Coke to some Coke. You won't pay nearly as much to go from some Coke to a lot of Coke — because you're not thirstier, you're just less thirsty than you were. McDonald's and Starbucks know this cold. Gruber walks through the actual math: a soda costs the company three or four cents to make. If they charge a penny more for the large and people still buy it, that's pure profit. Keep raising the large's price and, at some threshold, customers start downgrading back to the small — not because they can't afford it, but because the marginal cup of soda simply isn't worth that much to them anymore. Somewhere out there, an actual pricing team ran this exact experiment, penny by penny, until they found the number. He builds the whole framework from three assumptions most people have never seen written down, even though they use them every day: you always have an opinion between two options, your preferences don't contradict themselves in a loop, and more is always at least a little better than less. From just those three rules, he derives an entire mathematical map of what any person wants — the same tool an economist would use to model a soda purchase, a salary negotiation, or a decision between a better job in a boring city and a worse job somewhere you actually want to live. He calls it the "mom test": if you can't explain a concept from this lecture well enough to walk your non-economist mother through it, you don't actually understand it yet. MBA pricing consultants charge real money to explain why "upsize for 70 cents" works. It's the same idea a freshman economics class covers for free in the second week. The lecture is free. Noticing exactly where your own "worth it" turns into "not worth it" is the entire edge.
Beaver497,426 görüntüleme • 2 ay önce

this is absolutely f*cking insane Black Rock just leaked 4 GitHub repos that give you the trading desk a fund pays millions for: want a full research team arguing over every trade? -> TradingAgents: a multi-agent trading firm in one repo. analysts, researchers, a risk desk want the data terminal without the terminal bill? -> OpenBB: an open data platform for analysts, quants and AI agents want a bot that actually places the orders? -> freqtrade: free, open-source crypto trading bot with backtesting built in want all of it in one place? -> QuantDinger: an AI trading OS. research, Python strategies, backtest, paper and live trading ~282k stars of trading infrastructure. $0 in licences. now the part worth trying. every one of these has the same slow spot: the moment before the order, where something has to say yes or no. that's where Jev goes. it can't write a word. it returns BUY / SELL / HOLD with a probability in 70 to 500 milliseconds. QuantDinger already ships it as the pre-trade gate. and one repo, jev-trader, asks it buy or sell every ~300 ms and quotes a limit order on every single block. the stack in one line: OpenBB brings the data, the agents do the research, Jev makes the call, the bot places the order. the catch: fast is not the same as right. none of this is an ATM. paper trade it first. Jev + these five is the setup to test this month. bookmark and share with a friend
Beaver45,179 görüntüleme • 18 gün önce

It is becoming f*cking dangerous: I launched a full-fledged autonomous crawler that parses any website with ZERO LINES OF CODE Forget about Python, terminals, CSS selectors, and constant manual copy-pasting You can set up a seamless No-Code integration just once, where Claude becomes the brain of your automatic data collector, and the results automatically flow straight into your spreadsheets In this setup, a No-Code service accesses the website and grabs the raw content, while Claude instantly cleans out the noise, extracts the key insights, and organizes everything neatly How to set this up: 1. Pick a No-Code service: Sign up for makecom, zapiercom, or install the bardeenai extension (all of them offer free tiers) 2. Set up the Launch: Specify how often the crawler should run (for example, Every day at 9:00 AM or At the click of a button) and feed it the target URLs 3. Connect the Claude module: Add an AI step to your scenario and give Claude a clear instruction: "Analyze the provided page text. Extract product names, prices, discounts, and seller contact details. Return the data as a clean, structured list" 4. Choose where to save the results: Connect the final step (for instance, Google Sheets or Notion) Quick 5-minute setup, full 24/7 autonomy, and zero headache with code maintenance. Essentially, with just a few clicks you are creating your own smart AI agent that quietly handles the routine work while you focus on real tasks Bookmark this for later
Beaver34,419 görüntüleme • 21 gün önce

honestly this should be f*cking illegal your LLM takes 30 seconds to think about a trade, but candle closed 29 seconds ago. Jev answers in 70 to 500 milliseconds. it can't write a word. it returns BUY / SELL / HOLD and a probability, and that's all a scalp needs. 3 repos already built on it: -> jev-trader: one AI trade decision every single block, on a live MON-USDC market -> QuantDinger: a full open-source AI trading OS with Jev built in. research, strategy, agent trading -> AIStock: "one person can become their own super-analyst" $0.042 per million input tokens. output is free. that's thousands of decisions for the price of one LLM call. the catch: fast is not the same as right. a wrong call in 200 milliseconds is still a wrong call. paper trade it first. > let the big model do the research. > let Jev pull the trigger. > let code set the stop. bookmark this before your bot is the slow one in the room.
Beaver12,446 görüntüleme • 8 gün önce

Two horses. One has a 20% chance of winning, the other 80%. A bookie knows the real odds. The crowd doesn't. $10,000 lands on one horse, $50,000 on the other. Inside an MIT classroom, a professor asks one question: how does the bookie guarantee he never loses? He ignores what he knows. Sets the odds not by probability but by how the money fell. Five to one, matching the market. First horse wins, he pays $60,000 and collected $60,000. Second horse wins, same thing. Zero exposure. Fee on top. Riskless profit. That's not gambling. That's pricing. The same math prices every option contract on Wall Street. Black-Scholes, replicating portfolios, hedging. It starts with one insight: you don't need to predict the future. You structure the trade so the future doesn't matter. The professor builds it step by step. Take any derivative. Find a combination of stock and cash that replicates the pay-off exactly. Hold both sides. Risk cancels. You keep the spread. He pulls up Bloomberg with IBM call options and shows it in real numbers. Prices a digital option using nothing but two calls at different strikes. No model needed. Just replication. Traders do this thousands of times a day. Enter a contract, hedge it on the exchange, walk away with a fee. No opinion on direction. Just structure. The entire derivatives market works this way. Not prediction. Replication. The people who understood that distinction first built the biggest fortunes in finance.
Beaver70,042 görüntüleme • 2 ay önce
A Jev engineer hasn’t waited on a CI pipeline in three months, and his changes still reach production faster and safer than the rest of the team’s He never sped the pipeline up. He routed around it, letting every change prove itself on live traffic users never see. > SHADOW - each change runs beside production on a mirrored copy of real traffic > JUDGE - the Jev system compares both outputs request by request, never by averages > SWAP - a change that matches or beats live behaviour goes in, with a 200 ms rollback armed CI was built for a world where real traffic was too risky to touch, so it tests against guesses about what users do. Shadow traffic removes the guess. The new code sees exactly what users send, and its answers simply never reach them. The comparison is the hard part. Two outputs can differ and both be right, so Jev scores intent instead of exact matches. Most changes clear in minutes. The ones that fail get caught on the exact request that broke them, input attached. The armed rollback is what makes it safe. One bad response and the old path is back before the next request lands. His team still writes tests. They just stopped treating a green checkmark as proof that real users will be fine. His full setup, from the traffic mirror to the rollback trigger, is written up in the article attached here.
Beaver21,131 görüntüleme • 25 gün önce

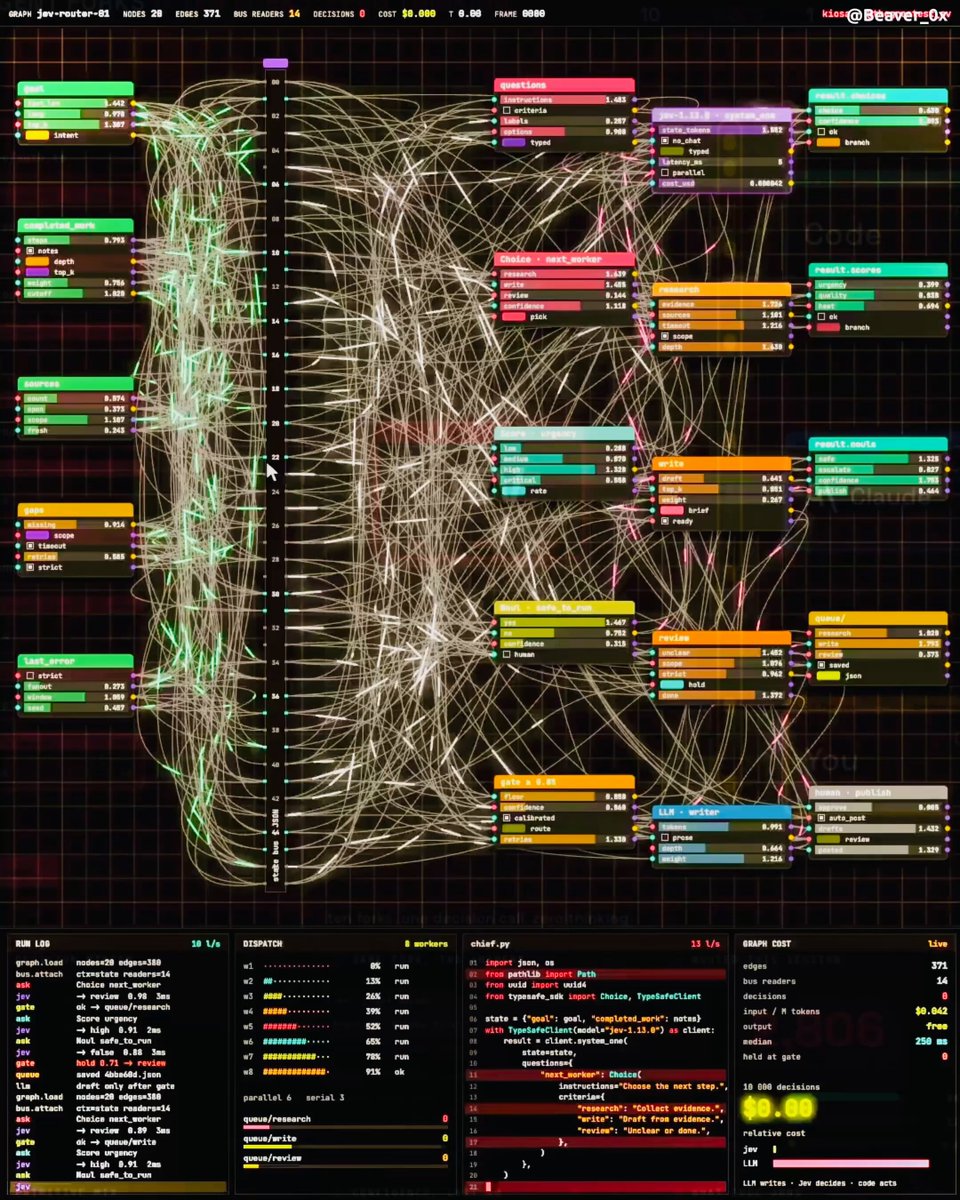
whoever built this realized we’ve been using our smartest AI for the dumbest possible jobs your $25-$250/mo frontier model is researching, writing code, planning… and then you’re paying the same brain to decide YES / NO. Jev flips that. it’s a tiny decision model that sits in front of the expensive stuff and handles the boring forks: -> which agent goes next? -> is this worth researching? -> reply or ignore? -> publish, wait or escalate? -> BUY / SELL / HOLD? -> click this or keep looking? then I saw the numbers people are reporting and the whole architecture started making a lot more sense. ~2,000 papers classified for around $0.05 ~800 emails sorted for around $0.028 browser-agent loops demonstrated around 6 seconds for ~$0.0029 and at the quoted pricing, roughly 20,000 ~2K-token decisions comes out around $0.62. that’s not because Jev became smarter than Claude. it’s because nobody asked it to be Claude. the setup is stupidly simple: -> big LLM gets the hard thinking, research and writing -> Jev gets the thousands of tiny decisions between those steps -> code actually clicks, saves, sends and executes and suddenly you start noticing these little decisions everywhere. > your inbox. > X feed. > support queue. > meetings. > leads. > video clips. > browser agents. > even paper-trading loops. that’s the part I think most agent builders are missing. the expensive model doesn’t need to touch every step just because it’s capable of touching every step. > let Claude think. > let Jev decide what deserves Claude. > let code do the actual work. I broke down 12 places you can wire this into an agent today + the exact router setup in the article below
Beaver19,716 görüntüleme • 29 gün önce

An MIT mathematician built the world's first wearable computer in 1961 to prove every casino on earth had been running roulette wrong for a hundred years. The device worked. He walked into a Nevada casino with it hidden in his shoe, played a single night, and beat the house edge before the earpiece wire snapped. Casinos rewrote their roulette rules within a year. Then he did the same thing to blackjack. Then to Wall Street. His name is Ed Thorp. He is 93. He beat Vegas at two games, ran a hedge fund for nineteen straight years without a losing quarter, and caught Bernie Madoff seventeen years before the SEC. The 92-minute interview in this video is Thorp at his home in Newport Beach explaining exactly how he did all of it. His personal fortune is estimated at $800 million. He earned every dollar from applying one 4-page paper written by an engineer at Bell Labs in 1956 The paper is called the Kelly criterion. It tells you the exact fraction of your capital to risk on any bet where you know the edge and the odds. John Kelly published it in the Bell System Technical Journal. It has been free in the archive for seventy years. Thorp read it, made one modification, and never lost money at scale again. The modification is called half Kelly. Full Kelly is the mathematically maximum bet your edge justifies. Half Kelly gives up a small fraction of return for a huge cut in drawdown. Every quant who blows up is running more than half Kelly. Every quant who compounds for decades is running less. Princeton Newport Partners, the fund he founded in 1969, compounded at roughly 20 percent a year for nineteen years. Not one losing quarter across the entire run. In 1988, at the top of his edge, he liquidated the fund and refused to open another. Every quant desk on Wall Street has spent the four decades since trying to reproduce what he did. Nobody has matched the runMonths In 1991 an investor asked Thorp to review Madoff's returns for a possible allocation. Within a week he had proof of fraud from reconstructing Madoff's trades against public exchange data. He sent a memo to the SEC. They filed it. Madoff ran the Ponzi for another seventeen years before his sons turned him in. "You can have enough. And it is better than not having enough." That is Thorp when journalists ask why he closed the fund at the peak. He had it. Almost nobody in his field ever does. The Kelly paper is free. Thorp's book "A Man for All Markets" is under twenty dollars. His 92- minute interview is on YouTube. Almost every hedge fund analyst has read the paper. Almost every retail trader has not. That is the entire moat. The math is free. The willingness to bet half of the maximum and walk away when it is enough is a much rarer commodity than the formula itself.
Beaver29,790 görüntüleme • 2 ay önce

this pure masterclass from Yale professor explains investment banking, breaking down decades of studying financial crises and showing why pure investment banking was fundamentally destroyed in 2008 when Lehman Brothers collapsed after a massive bank run on repo markets, giants like Goldman Sachs and Morgan Stanley were forced to give up their pure investment banking status just to survive this is the tape of his famous Yale lecture breaking down the brutal reality of Wall Street: • 03:46 - how investment banking differs from commercial banking • 12:45 - the secret principles of Goldman Sachs that built an empire • 17:19 - how Glass-Steagall split Wall Street in 1933 • 28:06 - how the shadow banking repo run brought down Lehman Brothers • 35:46 - what a 100 hour work week looks like for a Wall Street analyst • 53:56 - transitioning from investment banking to Silicon Valley giant Facebook bookmark & watch this rare lecture for free
Beaver12,481 görüntüleme • 2 ay önce
Daha fazla içerik yok.